By Victor Santos · OnPoint Mortgage Pro · Updated November 13, 2026
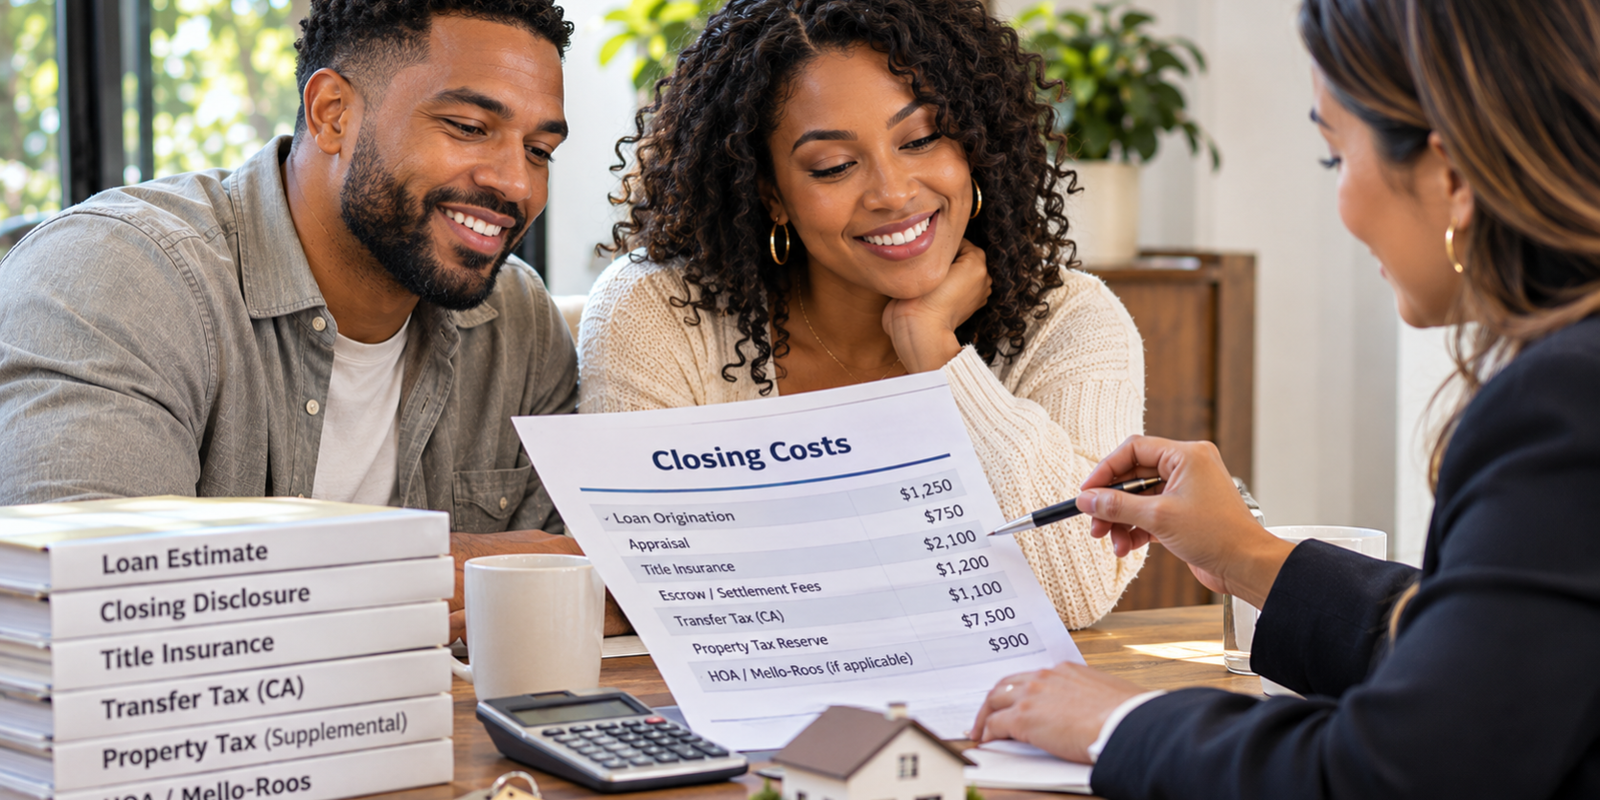
TL;DR: California buyers typically pay closing costs in the 2% to 5% of purchase price range, with high-end homes in Los Angeles hit by Measure ULA sometimes going far above that. On a $1,000,000 purchase in Orange County, that's roughly $20,000 to $50,000. The biggest line items for CA buyers are title insurance, escrow fees, documentary transfer tax, and prepaid property taxes and insurance. This guide walks every line item — what it is, who customarily pays, what it costs — and flags the three CA-specific surprises that catch first-time buyers after the escrow closes.
Who Pays What: California Custom vs. Negotiation
Every closing cost is negotiable in the purchase contract, but California has strong county-level customs that drive what sellers and buyers actually agree to:
- Southern California (LA, Orange, San Diego, Riverside, San Bernardino counties): the seller customarily pays the documentary transfer tax and the owner's title insurance policy.
- Northern California: the buyer customarily pays the documentary transfer tax and often the owner's title insurance policy.
- Escrow fees: typically split 50/50 statewide.
- Lender's title insurance: always paid by the buyer, statewide.
- Lender/origination fees, appraisal, credit report, prepaids: buyer, statewide.
These customs are starting points. In a slow market, buyers get sellers to pick up more. In a hot market, sellers get buyers to absorb more. The number on your Closing Disclosure is what the two sides actually agreed to in the purchase contract, not what “custom” says.
The Closing Cost Line Items
Lender and origination fees
Processing, underwriting, administration, and any origination charge the lender imposes. This is where lender shopping actually pays off — the gap between the cheapest and most expensive lender in this category can be $2,000+ on the same loan amount. Compare Section A of the Loan Estimate across every lender you quote.
Appraisal
Typically $600-$900 in California for a standard single-family appraisal. Jumbo loans, condos, and multi-unit properties run higher. Paid up front (not at closing) in most lenders' workflows.
Title insurance (owner's + lender's)
Two separate policies covering two different interests:
- Lender's title insurance (required): protects the lender's lien position against undiscovered title defects. Required by every mortgage lender. Buyer pays statewide.
- Owner's title insurance (optional but strongly recommended): protects you, the buyer, against the same risks — forged deeds, undisclosed heirs, missed liens, boundary disputes. In SoCal, custom has the seller pay this. In NorCal, custom varies.
If you get the two policies through the same title company simultaneously (simultaneous issue), you get a discount on the lender's policy. CLTA (California Land Title Association) is the standard owner's policy; ALTA (American Land Title Association) is the newer extended-coverage policy, required for the lender's policy.
Escrow / settlement fee
California uses independent escrow companies (not attorneys, as in East Coast states) for most residential transactions. Fees vary by company and transaction size; on a $750,000-$1,000,000 Orange County purchase, the buyer's half is commonly in the $500-$1,500 range. Escrow handles the money movement, document signing, title company coordination, and recording.
Recording fees
Paid to the county recorder to file the deed and mortgage. Typically $50-$250 in CA depending on county and page count.
California documentary transfer tax
Per California Revenue and Taxation Code § 11911, the state imposes a documentary transfer tax at $1.10 per $1,000 of value (or $0.55 per $500). On a $1,000,000 purchase, that's roughly $1,100 at the state base rate. Cities can impose their own additional transfer tax on top:
- General-law cities default to half the state rate ($0.55 per $1,000).
- Charter cities set their own rate — some are much higher.
In SoCal, custom has the seller pay this. In NorCal (especially San Francisco), it's frequently the buyer.
Los Angeles “Measure ULA” transfer tax
Within the City of Los Angeles specifically (not LA County generally), Measure ULA adds a sharply tiered transfer tax on higher-value properties:
- 4% on sales between approximately $5.4 million and $10.9 million
- 5.5% on sales above approximately $10.9 million
The thresholds adjust annually for CPI; the figures above are the current-cycle numbers, effective after June 30, 2026. The tax remains in effect: the California Court of Appeal upheld Measure ULA, and challenges continue at the California Supreme Court level. Do not plan around a repeal that hasn't happened. For luxury-tier LA sales, Measure ULA alone can be a six-figure line item.
Orange County city transfer taxes
Most Orange County cities are general-law cities and don't add a meaningful city-level transfer tax on top of the state base rate. The practical implication: closing-cost math in Irvine, Newport Beach, Costa Mesa, and most OC cities is far simpler than in LA at the same price point.
Prepaid property taxes
California's property tax fiscal year runs July 1 through June 30. Installments are due on a fixed schedule:
- First installment: due November 1, delinquent after December 10
- Second installment: due February 1, delinquent after April 10
At closing, the seller's share of the current tax period is credited to the buyer (or debited to the seller) in escrow. If your loan has impounds, the lender collects an initial reserve so there's cash on hand to pay the next installment when it's due.
Prepaid homeowners insurance
Buyers pay the first year's homeowners insurance premium at closing (12 months), plus a 2-month cushion into the escrow account if the loan has impounds. The 2-month cushion is the RESPA-permitted maximum per 12 CFR 1024.17(c)(5) — same rule we covered in our escrow guide.
Prepaid interest
Per-diem interest from the closing date through the end of that month. Close on the 5th of the month, pay 25 days of interest at close. Close on the 28th, pay 2 days. This is why late-month closings reduce the sticker-shock closing cost (though you still owe the interest either way).
Upfront mortgage insurance or funding fee (if applicable)
FHA, VA, and USDA loans each have an upfront fee:
- FHA: 1.75% upfront MIP, typically financed into the loan
- VA: funding fee of 1.25% to 3.3% depending on down payment and whether it's first or subsequent use, waived entirely for borrowers currently receiving VA disability compensation
- USDA: 1.0% upfront guarantee fee
- Conventional: no upfront fee; PMI is monthly only (unless single-premium PMI is chosen — see our PMI guide)
The Three CA Surprises That Hit After Closing
1. The supplemental property tax bill
When you buy a California home, the county reassesses it at the new sale price under Prop 13. The difference between what the seller was paying and what the reassessed bill is becomes the supplemental property tax bill. It typically arrives 3 to 9 months after closing.
Critical: supplemental tax bills are not impounded by your lender. Even if you have an impound account for the regular property tax, the supplemental bill is sent directly to you, the owner. You pay it out of pocket. See our escrow guide for the full breakdown of what impounds do and do not cover.
Budget for it. On a $1,000,000 OC purchase of a home that was previously assessed at $400,000, the supplemental catch-up bill can easily be $6,000-$8,000.
2. Mello-Roos (Community Facilities District tax)
Many newer SoCal developments (Irvine, Ladera Ranch, parts of Riverside and San Diego County) are in a Mello-Roos district authorized under California Government Code § 53311 and following. These districts levy a special tax (on top of regular property tax) to fund infrastructure like schools, roads, and parks. Mello-Roos can add 2-4% of the home's value annually, for as long as 30-40 years.
California Civil Code § 1102.6b requires the seller to disclose Mello-Roos before closing. Read that disclosure carefully. On a $1,000,000 Irvine home in a Mello-Roos district, the extra tax can be $5,000-$15,000 per year that you'll be paying for decades.
3. HOA transfer and capital contribution fees
If you're buying in a homeowners association, expect HOA-related closing items on top of everything else:
- HOA transfer fee: typically $200-$500 to update membership records. Can run $500-$1,500+ in larger or more sophisticated HOAs.
- Document prep fee: $100-$300 to produce the HOA disclosure packet required under California Civil Code § 4530.
- Capital contribution: many newer HOAs charge a one-time capital contribution (often 2-3 months of dues) at closing to seed the reserve fund.
- Prorated HOA dues: buyer pays the seller's unused portion of the current month's dues.
All of these show up on the Closing Disclosure, so there are no literal surprises — but they're line items first-time buyers routinely overlook when estimating “how much cash do I need at close.”
Seller Concessions: How Much the Seller Can Pay
Seller concessions (also called “interested party contributions” or “seller credits”) are money the seller can contribute toward the buyer's closing costs and prepaids. Caps vary by loan type:
| Loan type | Max seller credit | Note |
|---|---|---|
| Conventional, LTV >90% | 3% | Fannie Selling Guide B3-4.1-02 |
| Conventional, LTV 75.01-90% | 6% | Fannie Selling Guide B3-4.1-02 |
| Conventional, LTV ≤75% | 9% | Fannie Selling Guide B3-4.1-02 |
| Conventional, investment property | 2% | Any LTV |
| FHA | 6% | Excluding discount points and buydowns, per HUD ML 2024-06 effective 4/29/2024 |
| VA | 4% on reasonable value | Seller-paid customary closing costs are a separate uncapped category — VA buyers can often negotiate meaningfully more than the raw 4% implies |
| USDA | 6% |
In a buyer's market, pushing for the maximum seller credit is one of the most powerful levers you have. It can cover a rate buydown (lowering your monthly payment for the life of the loan), pay all your closing costs, or both.
Ways to Reduce Closing Costs
- Negotiate a seller credit inside the loan-type cap above. In a soft market, this is often your biggest lever.
- Lender credits. You can take a slightly higher interest rate in exchange for the lender paying some or all of your closing costs. Our No-Points buy-down is the most common OnPoint structure.
- Close later in the month to minimize prepaid interest (though you still owe the interest either way — this reduces the sticker amount at close).
- Shop lender fees aggressively. Section A of the Loan Estimate is where lender-to-lender variance lives. Compare it line by line.
- Zero-fee programs. Our Zero to Hero purchase option eliminates OnPoint's lender fees entirely for qualifying buyers (third-party costs still apply).
Quick Notes for Our Other 8 States
OnPoint is licensed in nine states. CA is our main market and gets the most detail above, but the closing cost picture shifts state to state:
- Texas: no state income tax but notable title insurance and higher property taxes affect prepaid amounts. Seller customarily pays title.
- Florida: documentary stamp tax of $0.70 per $100 on deeds (varies in Miami-Dade), plus intangible tax on the mortgage. Seller customarily pays the doc stamps.
- Virginia: grantor's tax of $1.00 per $1,000 (state) plus recordation. Buyer and seller roughly split.
- Maryland: state recordation + county transfer tax; buyer and seller customarily split the state recordation.
- Colorado: documentary fee of $0.01 per $100 (one of the lowest in the country).
- Idaho, New Hampshire, South Carolina: each has its own transfer tax / stamp duty structure.
For a full line-item estimate for your specific state and purchase price, we can run a personalized Loan Estimate.
Your Right to Review: The TRID Disclosure Timeline
Federal law guarantees two protection windows during the mortgage process (per CFPB regulation 12 CFR 1026):
- Loan Estimate (LE): delivered within 3 business days of your loan application. Shows the cost structure the lender is proposing.
- Closing Disclosure (CD): delivered at least 3 business days before consummation. Shows the final closing-day numbers.
Certain mid-process changes reset the 3-day CD clock: an APR change of more than 1/8% on a fixed-rate loan (or more than 1/4% on an ARM), a change in loan product (fixed to ARM, for example), or the addition of a prepayment penalty. If any of those happen, you get a new 3-day review window. Those are your protections — use the time to actually read the CD before signing.
Frequently Asked Questions
How much are closing costs in California?
Typically 2% to 5% of the purchase price, per Bankrate citing CoreLogic ClosingCorp data. On a $1,000,000 purchase, that works out to roughly $20,000 to $50,000. Luxury-tier sales in the City of Los Angeles can go far higher due to Measure ULA. The exact number depends on the loan type, down payment, lender fees, and how much the seller contributes.
Who pays closing costs in California — buyer or seller?
Both. Statewide custom: the buyer pays lender fees, lender's title insurance, appraisal, and prepaids. In SoCal, the seller customarily pays the documentary transfer tax and owner's title insurance. In NorCal the buyer often pays those. Escrow is usually split 50/50. Every item is negotiable in the purchase contract.
What is the California transfer tax?
California's state documentary transfer tax is $1.10 per $1,000 of value (per Rev & Tax Code § 11911). Cities can impose additional transfer tax on top. In the City of Los Angeles, Measure ULA adds 4% on sales above approximately $5.4M and 5.5% on sales above approximately $10.9M (current-cycle thresholds effective after June 30, 2026). In Orange County, most cities don't add meaningful city-level transfer tax.
What is the supplemental property tax bill?
A one-time bill that arrives 3 to 9 months after you close, reflecting the difference between the seller's old assessed value and your new purchase price under Proposition 13. It is not impounded by the lender. You pay it out of pocket, directly to the county. On a $1,000,000 purchase of a home previously assessed at $400,000, the supplemental bill can easily be $6,000-$8,000. Budget for it.
Can the seller pay all my closing costs?
Up to the loan-type cap. Conventional allows up to 3% at high LTV, 6% in the middle, and 9% at low LTV. FHA allows 6% (excluding discount points and buydowns). VA allows 4% in concessions on top of uncapped customary closing costs. USDA allows 6%. If you're negotiating in a soft market, pushing for the maximum seller credit is one of your most powerful levers.
What's the difference between the Loan Estimate and the Closing Disclosure?
The Loan Estimate comes within 3 business days of application and shows the initial proposed cost structure. The Closing Disclosure comes at least 3 business days before closing and shows the final actual numbers. Both are standardized 3-page documents required by the CFPB's TRID rule. Any significant mid-process change (APR shift above 1/8% on a fixed-rate loan, loan product change, or added prepayment penalty) resets the CD's 3-day window.
Are Mello-Roos taxes part of closing costs?
Mello-Roos is an ongoing annual tax, not a closing-day cost per se. But the seller is required to disclose it before closing (California Civil Code § 1102.6b), and the prorated portion for the current period shows up in escrow. It can add 2-4% of the home's value annually for as long as 30-40 years, so it's a factor in long-term budgeting rather than a one-time closing cost. Read the Mello-Roos disclosure carefully before you remove contingencies.
Can I roll closing costs into the loan?
Only in a refinance, where you have equity to work with. On a purchase, closing costs are paid either by you at close, by the seller as a credit (up to the cap above), or by the lender as a credit in exchange for a slightly higher rate. There is no “finance closing costs” option on a conventional purchase. FHA and VA upfront MIP / funding fee can be financed into the loan amount, but that's the fee itself, not third-party closing costs.
Bottom Line
California closing costs in the 2-5% range translate to meaningful dollars on today's home prices. The line items are mostly predictable — title, escrow, transfer tax, prepaids, lender fees — and they're all on the Loan Estimate and Closing Disclosure in a standardized format you can compare across lenders. The biggest misses for first-time CA buyers are the post-closing items: the supplemental tax bill, Mello-Roos (where applicable), and HOA capital contributions. Plan for them, then there are no surprises.
Want a personalized line-item breakdown for your specific price, down payment, and county? Call (877) 870-0007 or request a callback through our contact page. We'll run a Loan Estimate showing every line in writing, and walk you through what each one is before you commit.
OnPoint Mortgage Pro is a California-licensed mortgage broker (NMLS #888844, company NMLS #2134550, DFPI 60DBO-150320) serving California, Colorado, Florida, Idaho, Maryland, New Hampshire, South Carolina, Texas, and Virginia. Information in this article is for educational purposes only and is not legal, tax, or financial advice. Measure ULA thresholds, transfer tax rates, and property tax schedules are current as of publication date and may change. Consult a licensed real estate attorney or CPA for your specific transaction.
Equal Housing Opportunity.