OnPoint Signature Program
Zero to Hero
$0 points. $0 origination. $0 lender fees. On every purchase and every refinance. The money most lenders quietly charge you at closing stays right where it belongs — in your pocket.
$0
Points
$0
Origination
$0
Lender Fees
Three zeros. One simple promise.
These are the lender fees that pad most mortgage quotes. In the Zero to Hero program, all three are gone.
$0
Discount Points
No paying thousands up front just to buy your rate down. You get a competitive wholesale rate without the toll.
$0
Origination Fees
No 1% "origination" charge on your loan amount. On a $500K loan that alone is $5,000 you keep.
$0
Lender Fees
No underwriting, processing, or application "junk" fees. Zero fees from us, on purpose.
More than a no-points loan
A plain no-points loan removes the lender’s fees. Zero to Hero goes further: you choose whether to keep the lowest rate or keep your cash. Same program, your call.
Option 1 · Keep the lowest rate
No-Points
The lowest competitive rate, with none of the lender’s fees.
- $0 points, origination & lender fees
- Your lowest available wholesale rate
- You pay third-party costs (appraisal, title, settlement) in cash
Option 2 · Keep your cash
The Zero to Hero Credit
Choose a slightly higher rate and let the lender credit cover your closing costs.
- $0 points, origination & lender fees
- A slightly higher rate generates a lender credit
- That credit pays your appraisal, title & settlement charges
- Far less — sometimes zero — cash to close beyond your down payment
Short on cash, or planning to move or refinance in a few years? Option 2 can put thousands back in your pocket today. Staying long-term? Option 1’s lower rate wins over time. We’ll show you both, honestly.
How you go from zero to hero
The fees you don’t pay don’t just vanish — they turn into real advantages, whether you’re buying or refinancing.
🏡
More home, less cash
Buyers keep thousands for the down payment, reserves, or moving costs instead of handing it to a lender.
💰
Break even on day one
No points means no "how long until it pays off" math. Your savings start with payment number one.
📈
Refinance that makes sense
Homeowners can lower a rate without burning cash on fees, so a refi is worth it even for a smaller drop.
⚡
Nothing to recoup
Sell or refinance again in a couple of years? You’re not stuck trying to earn back money you spent up front.
Pick your path
Zero to Hero works the same way on both sides of a transaction. Start where you are.
🔑
Buying a home
Get into your home without lender fees eating your down payment.
- $0 points, origination & lender fees on your purchase loan
- Keep more cash for down payment and reserves
- Conventional, FHA, VA & more, priced from 20+ wholesale lenders
🔄
Refinancing
Lower your rate or tap equity without paying to do it.
- $0 points, origination & lender fees on your refinance
- Worth it even on a smaller rate drop — nothing to recoup
- Rate-and-term or cash-out, from our full lender network
How the credit covers your closing costs
No gimmicks. A lender credit is real money the lender puts toward your costs in exchange for a slightly higher rate — you’re simply choosing to pay over time instead of up front.
1
Pick a slightly higher rate
You choose to nudge your rate up a fraction of a percent.
2
The lender issues a credit
That higher rate creates a credit — the lender’s money, not a loan add-on.
3
The credit pays your costs
It goes straight toward appraisal, title & settlement charges at closing.
Appraisal + title + settlement
Your no-points rate
Slightly higher, from your quote
Enter the two rates your loan officer quotes. We assume the higher rate’s credit covers the costs above.
Option 1 · No-Points (par rate)
Rate6.00%
Monthly P&I$0
Cash for these costs$0
Option 2 · Credit covers costs
Rate6.50%
Monthly P&I$0
Cash for these costs$0
Enter your numbers to compare.
Illustrative only. Assumes the credit-option rate generates a lender credit that covers the closing costs you entered; your actual rate and credit come from a live quote. Break-even = the costs covered divided by the extra monthly payment. Payment is principal & interest only. Third-party costs shown are appraisal, title, and settlement; taxes, prepaids, and points are separate.
How can a broker charge zero lender fees?
Because we’re a broker, not a bank
OnPoint shops your loan across 20+ wholesale lenders. When one of them funds your loan, they compensate us — so we don’t need to charge you points, origination, or lender fees to get paid.
A retail bank has one product and makes its money on you. We make ours by winning your business against 20 other lenders. That competition is the whole advantage.
Straight talk: what “zero” covers
Always zero from OnPoint: discount points, origination, underwriting, processing, application fees.
Can be covered by the credit option: appraisal, title & settlement charges — in exchange for a slightly higher rate.
No one can waive: government recording & transfer taxes, and prepaids (homeowners insurance, prepaid interest, escrow deposits). Those aren’t lender charges.
The result: a genuinely lower cost to close — and the honest math on any rate-for-credit trade, with none of the "too good to be true" games.
Zero to Hero, answered
What exactly is $0 in this program?
Three specific lender charges: discount points, origination fees, and lender fees (underwriting, processing, application). On a typical loan those can run several thousand dollars combined. In Zero to Hero, they’re zero.
Does “zero fees” mean zero closing costs?
No — and we’ll never pretend it does. You still pay true third-party costs (appraisal, title/escrow, government recording and taxes, prepaid interest and insurance). Those belong to other parties, not to us. What we remove is the lender’s own fees.
What’s the catch? How does OnPoint get paid?
No catch. As a broker, the wholesale lender that funds your loan compensates us. That’s how we can charge you nothing and still shop 20+ lenders to find your best terms.
Do I get a higher interest rate in exchange?
Not for the $0 lender fees — that’s a competitive wholesale rate at par, and because we compare 20+ lenders it usually beats a retail bank’s rate after its fees. A higher rate only comes into play if you choose the credit option below to cover your closing costs.
What’s the difference between this and a plain no-points loan?
A no-points loan removes the lender’s fees at a par rate. Zero to Hero adds a choice: keep that lowest rate, or take a slightly higher rate so a lender credit covers your appraisal, title, and settlement charges too — keeping cash in your pocket at closing. Same program, your call.
Can OnPoint cover my closing costs?
Often, yes — through the credit option. A slightly higher rate creates a lender credit that goes toward third-party costs like appraisal, title, and settlement. You’re not getting them "free"; you’re choosing to pay over time via the rate instead of in cash up front. It’s a great move if cash is tight or you may move or refinance within a few years. Government taxes and prepaids (insurance, escrows) can’t be waived.
Is it for purchases, refinances, or both?
Both. Zero to Hero applies to home purchases and refinances alike — see the purchase and refinance paths above.
Who qualifies?
Most standard purchase and refinance scenarios across the nine states OnPoint is licensed in (CA, CO, FL, ID, MD, NH, SC, TX, VA). The fastest way to know is a quick, no-obligation conversation — no credit hit to check.
Heroes in Nine States
Verified Google reviews from the buyers and homeowners OnPoint has guided to the closing table — with zero lender fees.
EXCELLENT

Based on 80 reviews

Posted on Google 

NANA AMMA SERWAA BRONI
Trustindex verifies that the original source of the review is Google. If you like your current lender isn’t working hard for you, call Victor.I spent seven months shopping around and was nervous about making a move, but Victor’s transparency and expertise won me over.
While other leaders tried to push me into paying expensive points,Victor showed me why keeping my money and not buying down the rate was the much smaller move,
He took my payment form $3,302 down to $2,966 and handled all the complex FHA and Virginia State fees over $3,300 in lender credits to cover my closing costs.The level of service and honest advice here is night and day compared to the big banks. I finally feel like I have a mortgage pro I can trust.
Posted on Google

ron caringal
Trustindex verifies that the original source of the review is Google. Updated 060526:
I can’t recommend Victor's team enough! They managed to lower my interest rate by a full 2% and consolidated my high interest debts into one manageable payment. This move alone is saving me $830 every single month. On top of that, they secured $5,000 in lender credits, which covered all my closing fees and even left an excess to apply toward my prepaid interest. If you want a mortgage professional who actually delivers on their promises, call Victor.
Previous 12/2024:
Victor was easy to deal with. He made the effort to exhaust all possible means for him to meet my target loan amount given the predicament.
Posted on Google

Rubab Anees
Trustindex verifies that the original source of the review is Google. We did FHA streamline refinance with Victor and It was an awesome experience working with him.. Process was smooth and fast! Victor is knowledgeable and very professional. Our team to go for all future needs👍🏻
I can’t recommend Victor enough. He helped us navigate a refinance that lowered our interest rate from 7.125% to 5.875% in record time. Seeing our monthly payment drop by $528 is a huge relief for our family budget. Victor is professional, transparent, and clearly knows how to get the best results for his clients. We are so grateful for his help!
Posted on Google

Jordan Hill
Trustindex verifies that the original source of the review is Google. I had a great experience refinancing my home and highly recommend working with Victor. The entire process was smooth, efficient, and completed much faster than I expected.
They were communicative, transparent, and made sure I understood each step along the way. I was able to secure a lower rate and reduce my monthly payment, which made a meaningful difference.
What really stood out was the level of professionalism and how easy they made everything from start to finish. I also appreciate that they continue to monitor rates and stay in touch even after closing.
If you’re thinking about refinancing, you’ll be in good hands here!
Posted on Google

Joanna O
Trustindex verifies that the original source of the review is Google. We had an excellent experience working with Victor Santos at OnPoint Mortgage in Irvine, California for our second mortgage loan. If you’re looking for someone who is knowledgeable, efficient, and highly responsive, Victor is the person to trust.
From start to finish, the entire loan process was smooth and stress-free. Victor was always quick to respond, kept us updated every step of the way, and made sure we fully understood everything. His expertise in mortgage lending really shows, and it gave us a lot of confidence throughout the process.
What really stood out was how he went above and beyond, he even communicated directly with our HOA to gather all the required documents, which saved us so much time and hassle.
On top of that, Victor is friendly, professional, and easy to work with. We’re truly grateful for his help and would highly recommend Victor Santos and OnPoint Mortgage to anyone in Irvine or Orange County looking for a reliable and efficient mortgage lender, especially for second mortgage or home loan needs.
Posted on Google

Ernest Butch Benares
Trustindex verifies that the original source of the review is Google. I’m a returning customer with OnPoint Mortgage Pro, and once again they delivered an outstanding experience. Victor helped me in the past, and because that process was smooth and professional, I didn’t hesitate to work with him again.
This loan came at the perfect time for my wife and me. With unexpected expenses, inflation, and credit card interest rates climbing like crazy, we needed a real solution. I’m genuinely happy with the rate Victor secured for us. It allows us to pay off all our outstanding credit cards and finally get ahead instead of falling behind. It truly feels like we’re getting our financial footing back.
Victor handled everything with transparency, patience, and expertise. He made the entire process easy to understand and completely stress‑free. His professionalism and attention to detail are exactly why I trust him and his company with something this important.
If you’re looking for a lender you can trust, someone who genuinely looks out for your best interest, I highly recommend Victor and the team at OnPoint Mortgage Pro.
Posted on Google

Joyce Halim
Trustindex verifies that the original source of the review is Google. Victor is really a great guy. He helped me patiently step by step through the process of my refinance. Highly recommended. Thank you so much ☺️
Update:
I'm so happy that Victor helped me again with my refinance. And this is my third times, from the original 8.125% down to 5.75% smoothly. Wohoo....couldn't be more happier than that 😊....He is truly the guy that I can trust, rely on and do the magic. Highly recommended.
Thanks for the experienced.....and we will still work again in the future. 😊
Posted on Google

eunice chun
Trustindex verifies that the original source of the review is Google. We refinanced twice with Victor. He was so professional and very helpful throughout our loan process. Highly recommended!
Posted on Google

Rachel Turner
Trustindex verifies that the original source of the review is Google. Victor Santos was very professional, quick to respond, and easy to work with. The process was seamless and we would highly recommend Victor to work with for any financing or refinancing needs. This is the third time we have used Victor because of his kind, exceptional customer service, and the ease of communication. Such an easy process!
Posted on Google

Nick Tyndal
Trustindex verifies that the original source of the review is Google. Very friendly and quick on communication. Understood my needs and worked diligently until they were achieved. Would highly recommend and plan to use OnPoint again in the future.
Meet Your Mortgage Specialist
20+ years originating mortgages across every loan type, licensed since 2005. Same person from quote through closing.
VS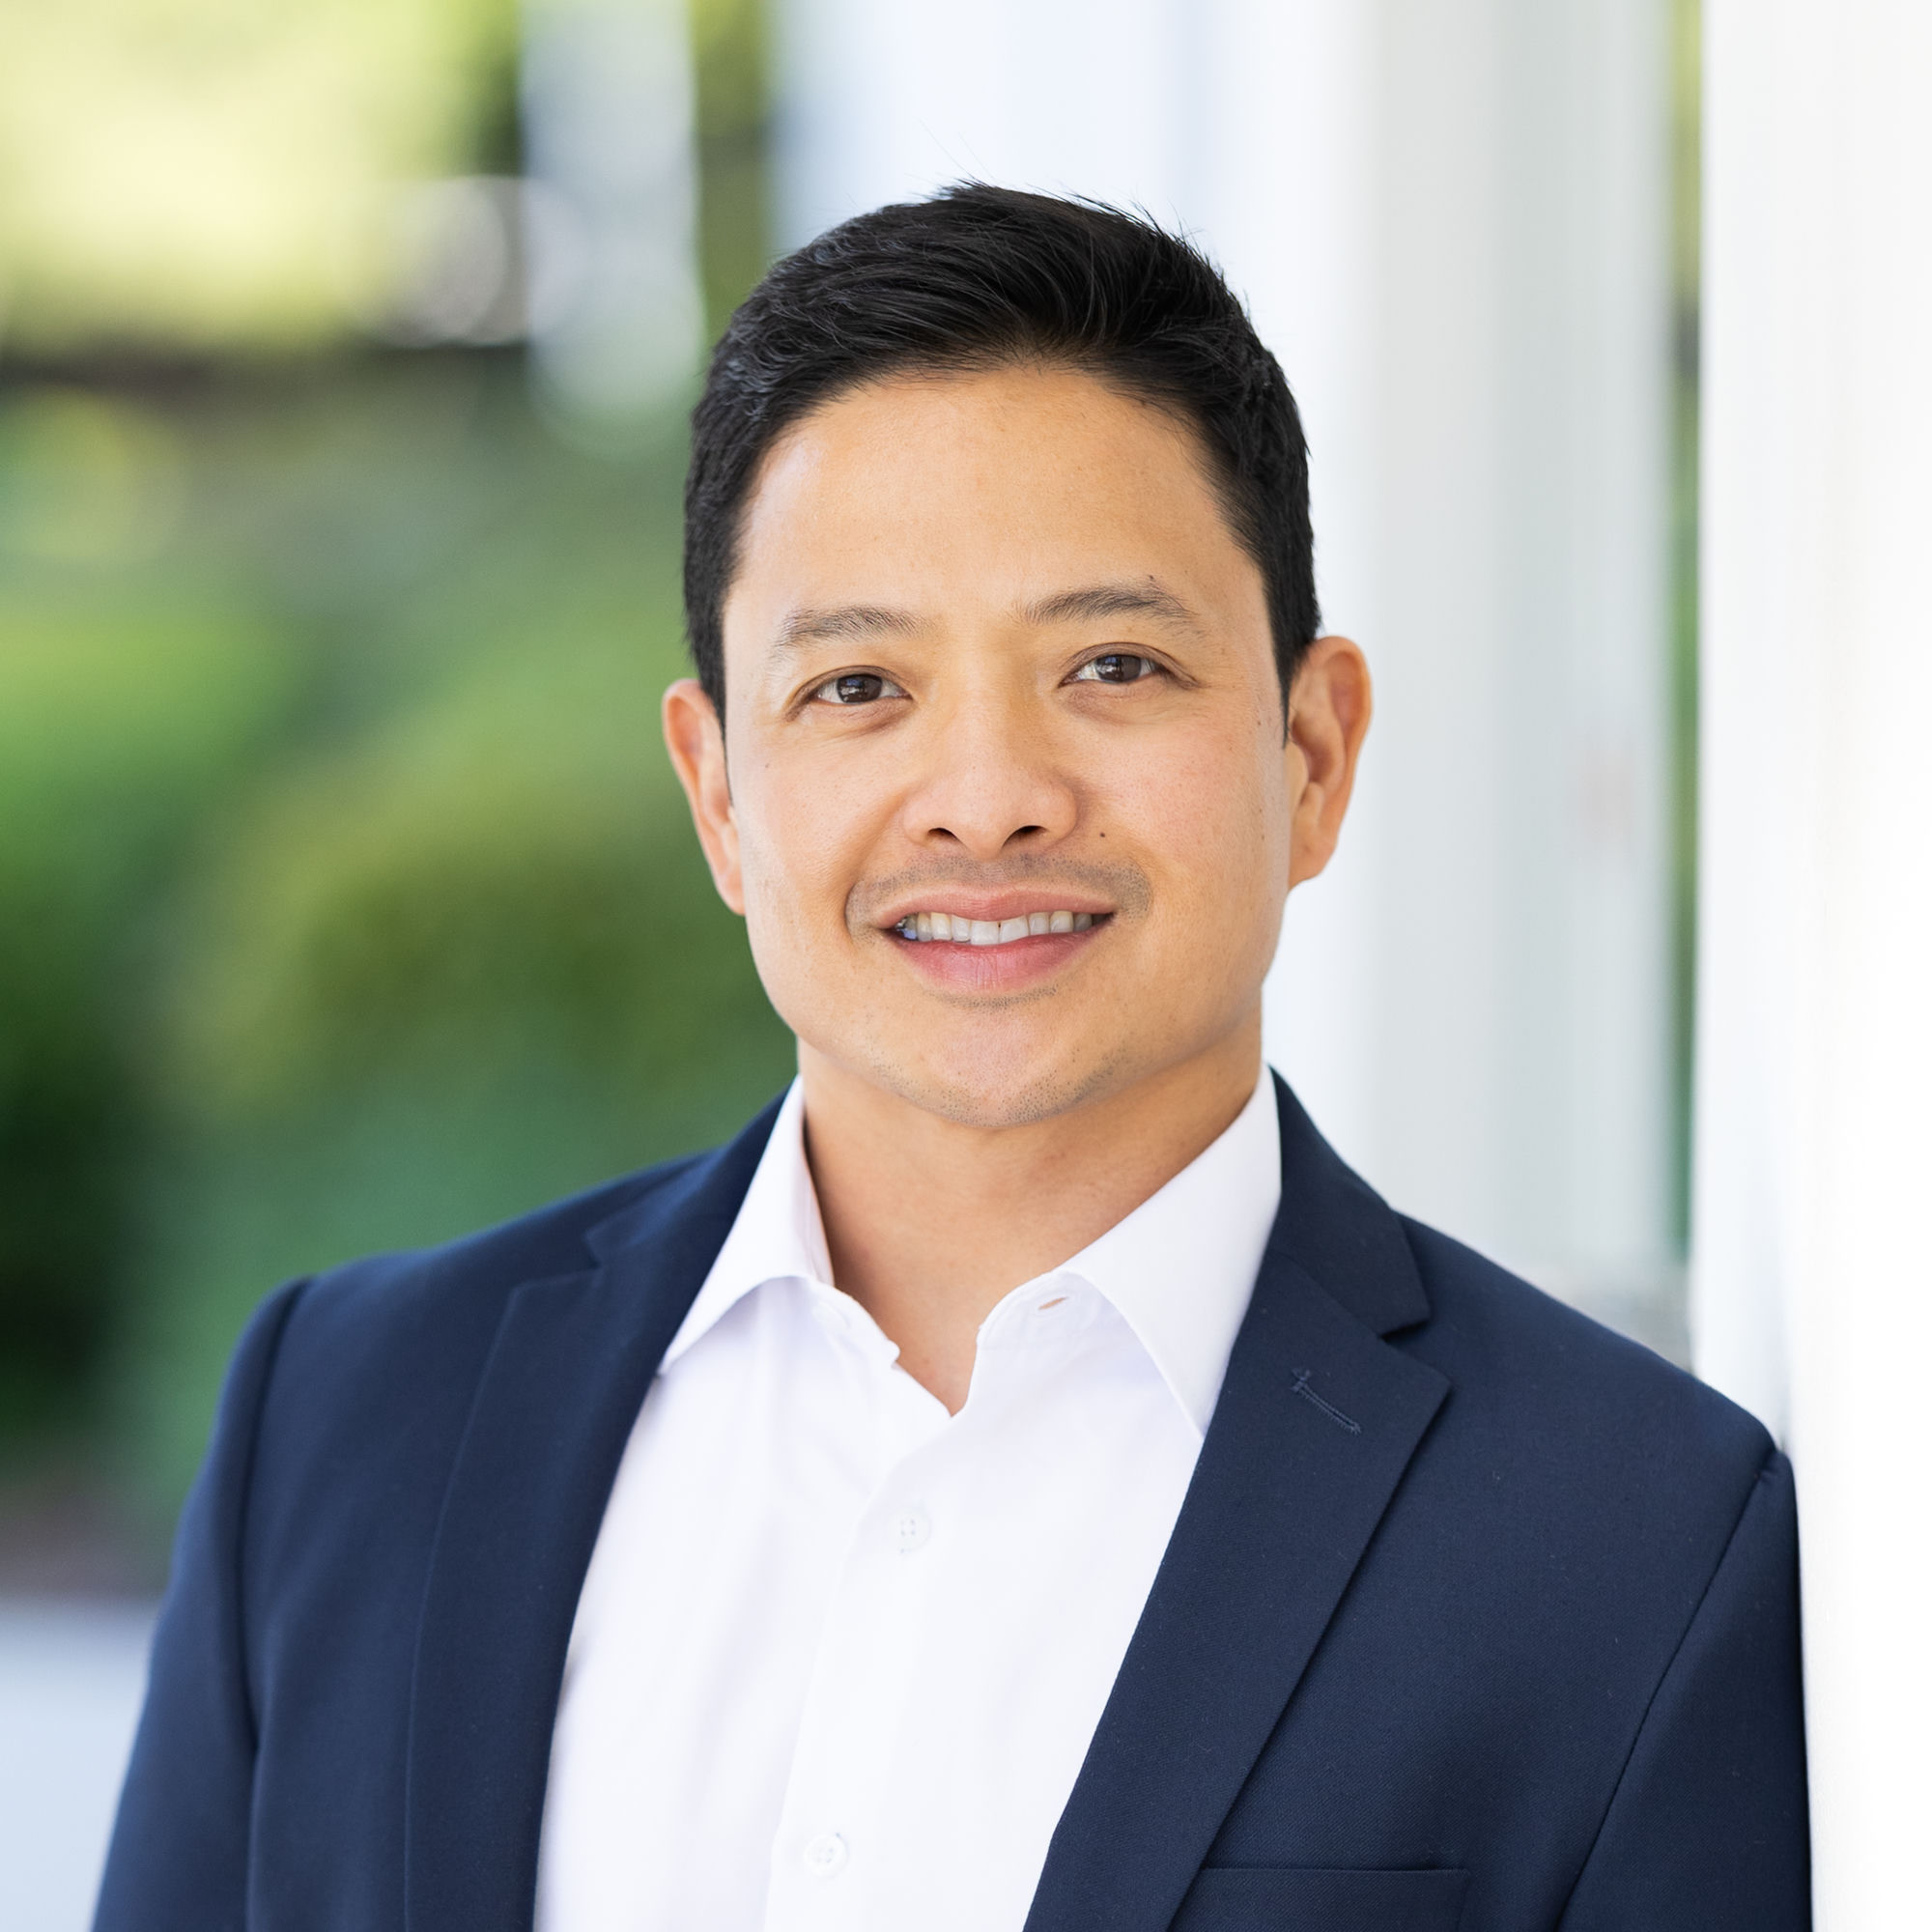
Victor Santos
SENIOR LOAN OFFICER · NMLS #888844
Victor entered mortgage in 2002 as a loan processor and has been writing loans as a licensed LO since 2005. He shops your file across 20+ wholesale lenders, including specialists for every loan type. He'll match you to the right program and the right lender, not just the first one that says yes.
Experience: 20+ yrs originating (LO since 2005)
Personal NMLS: #888844
Company NMLS: #2134550
Licensed in: CA, CO, FL, ID, MD, NH, SC, TX, VA
Ready to keep the fees and get the home?
Tell us whether you’re buying or refinancing and we’ll show you a real Zero to Hero quote. No pressure, no credit hit to look.
- ☎(949) 486-8200
- ✉info@onpointmortgagepro.com
- 📍530 Technology Dr, Ste 100, Irvine, CA 92618 · Mon–Fri 8:00am–5:00pm PT
- ★5.0★ on Google, Yelp & Zillow · A+ BBB · Licensed in 9 states
OnPoint Mortgage Pro · NMLS #2134550 · CA DFPI (CRMLA) License 60DBO-140540. Equal Housing Opportunity. Not a commitment to lend; all loans subject to credit approval and underwriting. Zero lender fees refers to no OnPoint points, origination, or lender fees; third-party closing costs still apply.