By Victor Santos · OnPoint Mortgage Pro · Published November 16, 2026
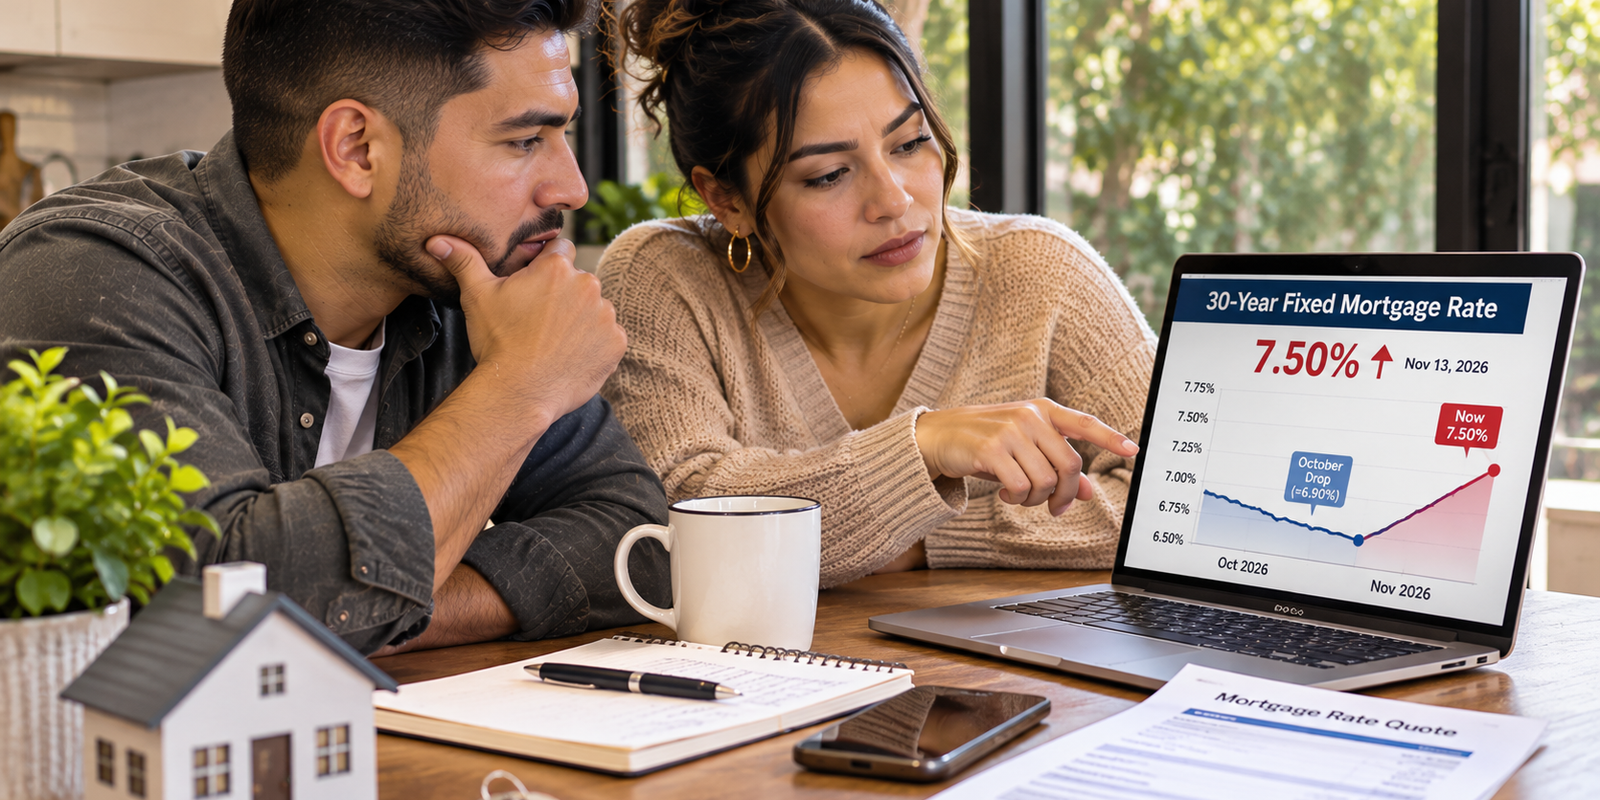
TL;DR: Mortgage rates spent all of October drifting down to around 6.9%, then wiped out the entire improvement in three trading days. Mortgage News Daily's 30-year fixed index hit 7.50% on Friday, November 13, and opened Monday at 7.51%. The 10-year Treasury had its biggest weekly jump since April 2025. The December Federal Reserve meeting now has about a 92% probability of a rate hike priced in. Here's what happened, why it happened, and what it means if you're actively shopping for a home.
What Just Happened: 60 Basis Points in Three Days
Through October, the 30-year fixed rate ground lower almost every week. By November 6, Mortgage News Daily's daily index showed the average top-tier 30-year at around 6.90% — the lowest in roughly five weeks. Buyers who had been waiting for a break finally had one.
Then came the three-day reversal:
- Tuesday, November 10: October CPI came in hotter than expected (headline +0.4% vs. +0.3% expected; core +0.3% vs. +0.2%). The third straight month of brisk inflation. The 10-year Treasury rose about 13 basis points to roughly 4.99%.
- Thursday, November 12: The 10-year Treasury pushed back above 5% (closing at 5.125%). New oil-market tension added to the move.
- Friday, November 13: MND's index hit 7.50%, up 0.33 percentage points on the week. The 10-year closed at 5.15%, its biggest weekly jump since April 2025.
- Monday, November 16: Opened at 7.51%, up another basis point, with the 10-year hovering near 5.13%.
In short: the rally October gave is gone. If you were quoted in late October around 6.9% and didn't lock, today's quote is roughly 60 basis points higher. On a $600,000 loan, that is about $240-$250 more per month — the kind of difference that can move a home from “yes” to “pause and rethink.”
Why the 10-Year Treasury Matters More Than the Fed
One point we spend a lot of time explaining to clients: the Federal Reserve does not directly set 30-year mortgage rates. The Fed sets the overnight federal funds rate, which influences short-term borrowing costs. Mortgage rates, which are long-term, follow the 10-year Treasury yield instead.
That's why last week's move was so sharp. The 10-year Treasury had its single largest weekly move in more than 18 months, and 30-year mortgage pricing moves roughly in sympathy. When bond investors demand higher yields on long-term Treasuries because they expect more inflation (or more Fed hikes, or a worse supply situation), mortgage rates climb with them.
What drove the 10-year higher? A combination of:
- Hot CPI on Tuesday that confirmed inflation isn't cooling as fast as the Fed hoped
- Oil price pressure on energy-market tensions late in the week
- A weak $42B Treasury auction on Monday that showed soft demand for new US government debt
- Fed speak that reinforced the expectation of more hikes rather than a pause
The December Fed Meeting: A Hike Is Priced In
As of Monday morning, the CME Group's FedWatch Tool shows about a 92% probability of a 25 basis point rate hike at the next Federal Reserve meeting on December 8-9, and about an 8% probability of a 50 basis point move. The Fed held at 3.75%-4.00% on October 28 in a 10-2 vote (Governors Cook and Hammack dissented in favor of a hike), and officials have been publicly pushing for more.
New York Fed President John Williams said last week that “inflation is far too high.” Dallas Fed's Logan has called for “at least two more” hikes. Fed Chair Kevin Warsh speaks today at noon Eastern Time. Markets will be listening closely to anything that shifts the December calculus.
Even though the Fed doesn't set mortgage rates directly, a longer and more aggressive hiking path keeps Treasury yields elevated — and keeps mortgage rates with them.
Why Freddie Mac Still Shows 7.11% (And Why That's Misleading)
Freddie Mac's weekly Primary Mortgage Market Survey (PMMS), released every Thursday, showed 7.11% for the 30-year fixed on November 12 — actually down 0.07 from the week before, and the fourth straight weekly decline. If you're relying on the Freddie number, you're seeing an “all is well” narrative that has nothing to do with today's market.
The reason is survey mechanics. Freddie Mac's PMMS is a week-long moving average collected from lenders, weighted toward the earlier days of the survey window. The November 12 release captured three low days (Thursday through Monday, when rates were still in the 6.9s) and only one higher day. The sharp Tuesday-Thursday jump lands in the next release, out this Thursday, November 19.
Translation: expect this Thursday's Freddie number to jump sharply. In the meantime, for what the rate market is actually doing today, daily indices (Mortgage News Daily, lender rate sheets, our own mortgage rates page) are the current signal, not the weekly PMMS.
What This Means If You're Actively Shopping
Different buyer situations call for different responses. Here's how we're framing conversations this week:
If you're in escrow and haven't locked yet
This is a lock-vs-float decision, and the math has gotten harder in the past week. Floating made sense through October because every day was slightly better than the last. That calculus is now inverted: floating risks another Fed-driven jump before close, with no obvious catalyst for rates to reverse before the December meeting. We're recommending that most clients with firm close dates in the next 30-45 days seriously consider locking now.
If you're actively shopping but haven't written an offer
Reset your budget at the new number before you write. A pre-approval letter issued in late October was likely priced in the 6.9s; at 7.5%+, the same monthly payment supports a meaningfully smaller loan. Pull a fresh pre-approval with current numbers (see our pre-approval guide), rerun the affordability math, and only then decide what price range makes sense.
If you paused in October to wait for lower rates
This is the hardest group. You waited. The improvement you were waiting for arrived, and now it's gone. The question is whether waiting another month, another quarter, another year is likely to get you a better outcome than acting now at 7.5%.
Honest answer: nobody knows. If the Fed hikes 25 basis points in December and signals more coming, rates could grind higher. If inflation surprises to the downside or growth stalls, rates could drop again. Our view on when rates might move lower (and what would have to happen) is laid out on our rates outlook page, and the full “should I wait vs. buy” decision framework is on our should-I-wait page. Short version: waiting has costs too — rent paid, missed appreciation, moving-target home prices — and those costs are real regardless of what rates do next.
If you're a refi shopper who was close to pulling the trigger
If you had a break-even window that just closed because rates jumped, run the math again before you give up. Our refinance calculator handles the current-vs-new rate comparison and shows your break-even timeline. Some scenarios — dropping PMI, consolidating a higher-rate second mortgage, pulling cash out at any rate — still work even in this environment.
What to Watch This Week
Several data points this week could push the rate narrative either direction:
- Monday, November 16: Fed Chair Warsh speaks at noon Eastern. Watch for any shift in tone on December.
- Tuesday, November 17: Retail Sales (October) at 8:30 AM Eastern. A hot number reinforces the hike case; a weak number could cool rates slightly.
- Wednesday, November 18: FOMC minutes from the October 27-28 meeting at 2:00 PM Eastern. Markets will parse these for how many officials wanted to hike that day (we know two dissented in favor).
- Thursday, November 19: Freddie Mac PMMS at noon. This is the number that will finally “catch up” to the daily market and likely show 7.3%-7.5%.
- Friday, November 20: University of Michigan consumer sentiment and inflation expectations. Consumer inflation psychology matters to the Fed.
The bigger set-piece ahead is the FOMC decision itself on Wednesday, December 9, with the November jobs report on December 4 and November CPI on December 10 setting the final table.
OnPoint's Take
We're not in the business of predicting the market, and we won't tell you that rates are definitely going up (or down) from here. But we can tell you that the easy “just wait a few weeks” answer that worked through October no longer does. The Fed is explicitly tightening, and until inflation data softens or growth stalls meaningfully, the path of least resistance for rates is sideways to higher.
For the latest numbers on our actual posted rates (updated by our Daily Rates team, not restated here), see our mortgage rates page. If you're a current client in escrow, we'll be calling to discuss lock timing this week. If you're actively shopping and want a soft-pull pre-qualification at today's numbers (see our credit score guide for why that matters), that's a 10-minute conversation. Call (877) 870-0007 or request a callback through our contact page.
Frequently Asked Questions
Why did mortgage rates jump in November 2026?
Three factors stacked in three days. Hot October CPI (Nov 10) confirmed inflation isn't cooling fast enough. The 10-year Treasury pushed back above 5% on inflation data and oil-market pressure. And expectations for a December Fed rate hike became fully priced in. The result: Mortgage News Daily's 30-year fixed index moved from around 6.90% to 7.50% in three trading days.
Is the Fed going to hike rates in December?
As of Monday, November 16, the CME Group's FedWatch Tool shows about a 92% probability of a 25 basis point hike at the December 8-9 FOMC meeting, and about an 8% probability of a 50 basis point hike. The Fed held at 3.75%-4.00% in October in a 10-2 vote, with two governors dissenting in favor of a hike. Multiple Fed officials have publicly pushed for more hikes.
Should I lock my mortgage rate now?
If you have a firm closing date in the next 30-45 days and haven't locked, the balance of risk this week favors locking. Floating worked through October because every day was better than the last; that trend has reversed, and there's no obvious catalyst to reverse it again before the December Fed meeting. If your close is farther out, talk to your loan officer about extended-lock options and the cost-benefit of those.
What happened to October's lower rates?
They're gone. The 30-year fixed index drifted from around 7.3% in early October down to 6.90% by November 6, and then reversed almost all of that drop in three days (November 10-13). As of Monday, November 16, the daily index is at 7.51% — actually slightly above where rates started October.
When will mortgage rates go back down?
Nobody knows with certainty. The honest answer requires either (a) inflation data that surprises to the downside, (b) growth or labor-market data that stalls meaningfully, or (c) the Fed signaling a pause or pivot. None of those are expected in the next 30 days. Our full outlook is on our rates timeline page.
Bottom Line
October's drop is erased. The daily market is sitting at 7.5% with the Fed widely expected to hike again in three weeks. Buyers who were close to acting now face a real decision — one that depends on your specific timeline, budget, and the opportunity cost of waiting longer.
If you want help running the numbers for your situation at today's rates, call (877) 870-0007 or use our contact page.
OnPoint Mortgage Pro is a California-licensed mortgage broker. In the mortgage industry since 2002, licensed loan officer since 2005. NMLS #888844 (Victor Santos), Company NMLS #2134550, Licensed by the Department of Financial Protection and Innovation under the California Financing Law, License #60DBO-140540. Serving California, Colorado, Florida, Idaho, Maryland, New Hampshire, South Carolina, Texas, and Virginia. Rates referenced in this article are averages from Mortgage News Daily and Freddie Mac, change daily, and are not offers or guarantees of rates OnPoint can offer any specific borrower. For OnPoint's currently posted rates, see our mortgage rates page. Information in this article is for educational purposes only and is not legal, tax, or financial advice.
Equal Housing Opportunity.