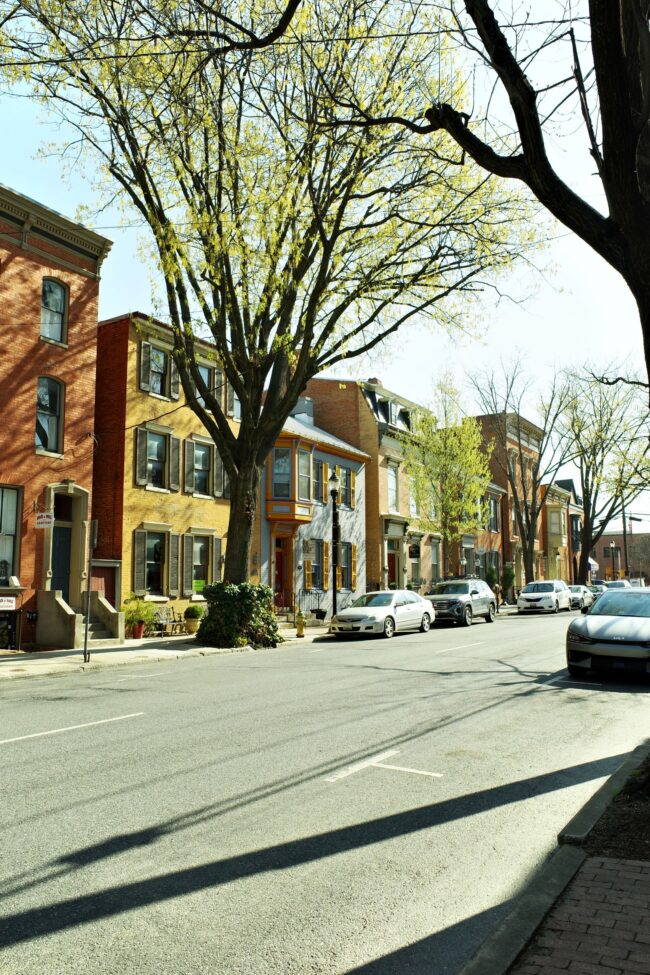
Historic Maryland row houses in Frederick under blossoming trees, representing the distinctive MD residential architecture where homeowners access equity through HELOCs

Maryland HELOC 2026: DC Suburbs, Baltimore Metro, and the Ground Rent Wrinkle No Other State Has

Maryland HELOC has three market realities (DC suburbs / Baltimore metro / Eastern Shore) plus one nationally-unique wrinkle — ground rent affects roughly 85,000 Maryland properties. A wholesale broker walks through 90% CLTV standard, high state + local income tax boosting itemization value, ground rent title complications, Baltimore rowhouse appraisal specifics, and worked $850K Bethesda + $380K Baltimore County scenarios.
Classic Virginia brick colonial home, representing the established equity Northern Virginia and coastal VA homeowners can access through a HELOC

Virginia HELOC 2026: The Two-Market Playbook (NoVA, Coastal Military, and the Rest of the State)

Virginia is really two HELOC markets — NoVA / DC metro high-value + coastal military / VA loan audience + central-western middle market. A wholesale broker walks through the state-specific rules including 90% CLTV standard, non-judicial foreclosure pricing, VA loan + HELOC layering strategy, historic district appraisals, and Chesapeake Bay Preservation considerations. Includes worked $900K Fairfax and $475K Virginia Beach military family scenarios.

Colorado Front Range home near Denver, representing the equity Colorado homeowners have built through years of strong appreciation and can access through a HELOC

Colorado HELOC 2026: Why the Front Range Is One of the Friendliest HELOC Markets in the Country (Rules, LTV, and Worked Scenarios)

Colorado’s low property tax (0.51%), strong Front Range appreciation (5-8% annual), and non-judicial foreclosure make it arguably the friendliest HELOC market in our 9-state footprint. A wholesale broker walks through the 7 Colorado-specific factors — standard 90% CLTV, low property tax, appreciation-driven equity growth, non-judicial foreclosure pricing, wildfire zones, mountain second-home rules, and STR income qualification — with worked $650K Denver metro and $1.2M Vail scenarios.

Charming Florida home with palm trees, representing the equity Florida homeowners can access through a HELOC despite the state insurance market challenges

Florida HELOC 2026: The Insurance-First Playbook (Rules, LTV Limits, and Worked Scenarios for Florida Homeowners)

Florida HELOC underwriting in 2026 is dominated by the state’s insurance market crisis, coastal LTV limits, and specific second-home rules. A wholesale broker walks through the 6 Florida-specific factors — insurance-first underwriting, county LTV differences, second home eligibility, no state income tax effect on itemization, judicial foreclosure, and homestead protections — with a worked $500K Miami-Dade scenario.

Suburban Texas home in Houston, representing the equity built by Texas homeowners exploring HELOC options under Article XVI constitutional rules

Texas HELOC 2026: What Article XVI Actually Means for Your Home Equity (Rules, LTV Cap, and Worked Scenarios)

Texas HELOC rules are legally stricter than every other state — 80% LTV cap (vs 90% elsewhere), mandatory 12-day waiting period, owner-occupied primary only, one HELOC per year per property, 3% fee cap, judicial foreclosure only. A wholesale broker’s plain-English walkthrough of Article XVI Section 50, with a worked $650K Frisco vs California comparison and the OnPoint Texas HELOC application process.

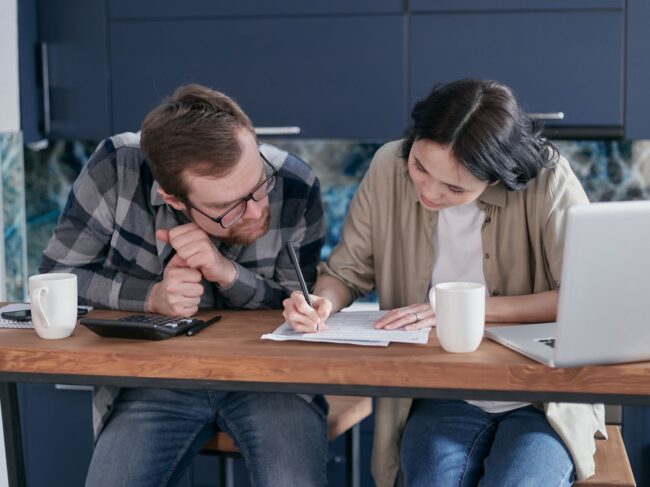
Young couple at kitchen table reviewing paperwork with a laptop and calculator, deciding how much house they can afford

How Much House Can I Afford? The 2026 Wholesale Broker Guide (With a Worked $180K Income Scenario)

How much house can you really afford in 2026? A wholesale broker walks through the two constraints that cap your purchase price (DTI + cash to close), the worked Orange County scenario ($180K income, $85K saved, $450/mo car), and the program-by-program comparison (conv 5/10/20% down, FHA, VA) that shows why max home price varies by $150K+ depending on your loan program.

Rent vs Buy: The Honest Math for 2026 — A $5,000 Renter vs an $800,000 Home Purchase

Should you rent your $5,000/month apartment or buy an $800,000 San Diego home with 10% down? A wholesale broker’s honest rent vs buy analysis: year-1 monthly cost comparison, year-10 total wealth comparison, break-even year framework, Prop 13 impact, and the 3 mistakes online calculators make. Includes a worked San Diego scenario with a link to our free Rent vs Buy Calculator.

Family sitting on the lawn at sunset watching their new home

Essential 2026 Mortgage Planning: A Family’s Complete Guide to Buying, Refinancing, and Building Wealth This Year

2026 is a decisive year for American families thinking about a mortgage. Rates are stable in the 6.0-6.5% range but not returning to the 3% floors of 2020-2021. Home prices are stable or modestly rising despite the higher rate environment. And a new generation of buyers — young families starting to grow, professionals relocating for hybrid-work opportunities, retirees downsizing — is reshaping demand across every state. The mortgage decisions you make in 2026 will affect your family’s wealth trajectory for the next 30 years. This guide is the essential 2026 mortgage planning framework: understanding today’s rate environment, choosing between loan programs, sourcing your down payment intelligently, managing the rate transition through refinance positioning, and making the strategic choices that turn a house purchase into a wealth-building decision.