By Victor Santos · OnPoint Mortgage Pro · Published November 17, 2026
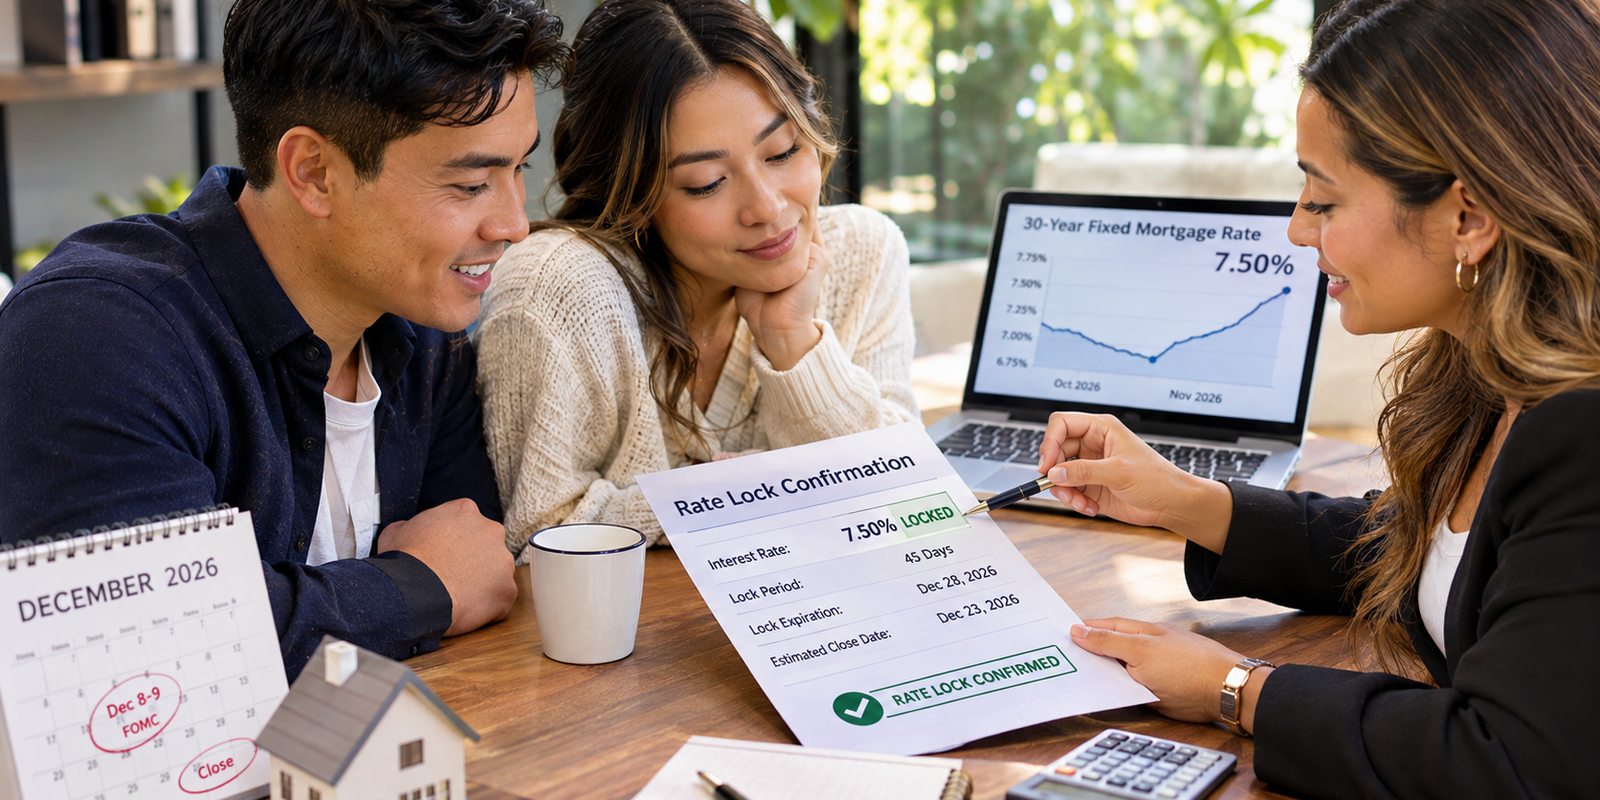
TL;DR: A mortgage rate lock is a lender's written commitment to hold a specific interest rate for a specific loan during a specific window of time (the CFPB cites 30, 45, and 60 days as the typical options; shorter and longer are lender-specific). It doesn't lock closing costs, doesn't guarantee underwriting approval, and doesn't protect you from appraisal issues. With 30-year fixed rates sitting near 7.5% in mid-November 2026 and the Fed widely expected to hike again on December 9, the lock-vs-float decision has gotten sharper — and this guide walks through how to make it.
What a Mortgage Rate Lock Is (and Is Not)
A rate lock is the lender's agreement to set aside a specific interest rate and pricing (points and credits) for your loan for a defined period. When you sign the lock, the lender takes on the market risk of that rate for the duration of the window: if the market moves higher, that's on them; if the market moves lower, you keep the rate you locked (unless you have a float-down option — see below).
What a rate lock does not do:
- It does not lock your closing costs. Third-party fees (title, escrow, appraisal, recording, transfer taxes, prepaids) can shift. Our closing costs guide walks the full line-item breakdown.
- It does not guarantee that your loan will close. If your income, assets, credit, or appraisal change materially, the underwriter can still deny the file.
- It does not lock the APR as a separate number. The APR is derived from the rate plus the finance charges; if your fees or loan amount change, the APR can move even when the rate itself is locked.
- It is not the same as a pre-approval. The CFPB puts it plainly: “A preapproval or prequalification letter shows how much a lender is generally willing to lend you. It is not a guaranteed loan offer.” Pre-approval is a qualification; a rate lock is a price commitment on a specific loan for a specific property.
When You Can Lock
Most lenders won't lock until you have a specific property identified and under contract. That's because the lock is tied to a specific loan file — loan amount, property address, program — and those variables aren't fixed until you're in escrow.
Some lenders offer “lock and shop” programs that allow you to lock a rate for 60 to 90 days before you've found a property. These are useful if you're actively shopping in a rising-rate environment but haven't written an offer yet. The trade-off is usually a slightly higher rate (to compensate the lender for the longer market risk window) and potentially a fee. Not every lender offers these programs; ask upfront if you want this option.
Standard Lock Periods
The CFPB's consumer guidance says rate locks are “typically available for 30, 45, or 60 days, and sometimes longer.” In practice, lenders offer a sliding scale:
- 15 days: same-cycle locks for files already clear to close. Cheapest; requires a file that is fully documented and close to funding.
- 30 days: standard refinance lock when the title and appraisal are already in hand.
- 45 days: most common purchase lock, matching typical escrow timelines.
- 60 days: longer purchase lock for slower-moving transactions or when the file has conditions outstanding.
- 90 to 120 days: new-construction locks or lock-and-shop programs. Priced meaningfully higher.
The pricing rule of thumb: longer locks cost more. Going from a 30-day to a 60-day lock on the same loan typically adds somewhere in the range of 0.125% to 0.375% in points or a correspondingly higher rate. Exact numbers vary by lender and market conditions.
The CFPB TRID Disclosure Rule (Why You Get a Revised Loan Estimate After Locking)
Federal law requires the lender to send you a revised Loan Estimate within 3 business days of the date you lock your rate. This is in 12 CFR 1026.19(e)(3)(iv)(D), the TILA-RESPA Integrated Disclosure (TRID) rule.
The revised LE confirms the locked rate, the points you paid (or lender credits you received), the fees, and the APR at lock. Keep it. The revised LE is your written record of the lock terms, and it's the document to reference if anything on your Closing Disclosure doesn't match what you expected.
Related: certain changes between the Loan Estimate and the Closing Disclosure trigger a new 3-business-day CD review window — specifically when the APR becomes inaccurate under 12 CFR 1026.22 (more than 1/8% off on a regular transaction, or more than 1/4% on an irregular transaction such as one with multiple advances or irregular payment periods), when the loan product itself changes (fixed to adjustable or vice versa), or when a prepayment penalty is added. A plain-vanilla rate lock that confirms what the first LE disclosed does not trigger a new 3-day window.
If the Lock Expires Before Closing
Lock extensions are common. If your closing date slips and the lock is about to expire, you have three typical paths. These are lender conventions, not a federal rule — ask your lender's specific expired-lock policy in advance:
- Extend the lock for a fee. Industry-typical extension fees run roughly 0.125% to 0.375% of the loan amount per 7- to 30-day extension window. Exact numbers are lender-specific.
- Re-lock at the current market rate. If current pricing is better than the original lock, this works in your favor. If current pricing is worse, it hurts.
- “Worse-of” pricing. Some lenders apply the higher of the original locked rate or the current market rate. This is the most conservative (and least borrower-friendly) convention.
The CFPB notes that extensions “may be expensive.” The best defense is avoiding the problem: pick a lock window that actually matches your closing timeline, with a few days of buffer. If you're in a 45-day escrow, don't take a 30-day lock.
Float-Down Options
A float-down is a one-time option to re-price your locked rate lower if market rates fall meaningfully during the lock period. Common parameters:
- Trigger threshold: market rates must drop by a lender-specified amount (commonly 0.25% or more) from the locked rate.
- Timing restriction: often available only during a specific window within the lock (e.g., after an appraisal is in, before 10 days to close).
- Cost: either an upfront fee paid at lock, or baked into a slightly higher starting rate. Not every lender offers float-down; those that do price it differently.
If the market is clearly trending lower and you have the timeline to wait, floating (not locking) can be a better move than paying for a float-down option. But in an environment like this week — where rates jumped 60 basis points in three days — a float-down is insurance you buy because the market is actively volatile, not because you're predicting a drop.
The Lock-vs-Float Decision: A Framework
Locking is not a prediction; it's risk management. The question isn't “will rates go up or down?” (no one knows). The question is “which outcome can I afford to get wrong?”
Locking usually makes sense when:
- Your closing date is firm and inside the lock window
- The current rate fits your budget and you can't absorb a meaningful rate increase before close
- Market momentum is upward (rising rates, hot inflation data, Fed hiking cycle)
- You've seen the Loan Estimate and you're ready to commit
- Your file is ready to move; only property-specific items remain
Floating usually makes sense when:
- Your closing date is 60+ days out and lock options don't reach
- Rates are clearly trending lower (not just one calm day)
- You could absorb a 25-50 basis point increase without derailing the loan
- You're pre-approved but not yet under contract
- Your lender doesn't offer a cost-effective lock-and-shop option
November 2026 context
This week specifically: rates have given back almost all of October's improvement, the 10-year Treasury had its biggest weekly move in more than 18 months, and the market has fully priced in a December 9 Fed rate hike. Our full breakdown of what happened is on our rates-erased post. The balance of risk this month favors locking for most clients with firm close dates. That calculus will shift as the Fed path becomes clearer, but today's lock-vs-float question is harder than it was in October.
For our longer-term rate outlook (what would have to happen for rates to go back down), see our rates timeline page.
How Your Credit Affects the Rate You Can Actually Lock
The rate a lender locks you at isn't the rate on the billboard; it's the rate your specific file prices to. FICO, LTV, loan type, DTI, property type, occupancy, and the current LLPA matrix all drive what you actually get. Our credit score guide walks through the pricing-tier math, including the September 9, 2026 VantageScore 4.0 addition at Fannie and Freddie.
Translation: pulling your FICO up one tier before you lock (740 to 760, for example) can save real money over the life of the loan — and the time to do that is before you're at the lock desk, not after.
Refinance Locks
Refinance rate locks work the same way as purchase locks, with a few practical differences:
- No purchase contract or seller timeline to coordinate; you control when to lock.
- Shorter lock windows (15-30 days) are more common because the file is simpler.
- The rescission rule (3-day right to cancel on primary-residence refinances under Reg Z) means your funding date is at least 3 business days after closing, so your lock needs to cover that too.
- Float-down availability tends to be better on refinance locks than on purchase locks, because the timeline is more predictable.
If you're running the lock-vs-float math on a refinance, our refinance calculator handles the break-even analysis.
How OnPoint Handles Rate Locks
We don't make predictions about where rates are going — nobody honest does. What we do is walk every client through the specific lock-vs-float decision on their file, with the actual market data and their actual timeline on the table. If you have a firm close date in the next 30-45 days and today's rate fits your budget, the conservative move is usually to lock. If you have months of flexibility and can absorb some rate movement, floating has upside.
For OnPoint's current posted rates (updated daily by our Daily Rates team, not restated here), see our mortgage rates page. For the broader buying-or-waiting decision, our should-I-wait page walks through the trade-offs in detail.
Frequently Asked Questions
What is a mortgage rate lock?
A mortgage rate lock is the lender's written commitment to hold a specific interest rate and pricing for a specific loan during a defined window of time — typically 30, 45, or 60 days per the CFPB. The lock protects you if market rates rise during the window; it also means you give up the benefit of a drop (unless you have a float-down option).
How long does a rate lock last?
Standard lock windows are 30, 45, and 60 days per CFPB guidance. Shorter 15-day locks are available on files that are already clear to close, and longer 90-120 day locks are common on new construction or lender-specific lock-and-shop programs. Longer locks typically cost more in points or a higher starting rate.
Can I lock my mortgage rate before finding a house?
Sometimes. Some lenders offer “lock and shop” programs allowing a 60-90 day lock before a property is identified. These typically cost more than a standard lock (higher base rate or upfront fee) and are useful in rising-rate environments. Not every lender offers them; ask upfront.
What happens if my rate lock expires before closing?
Three common lender outcomes: extend the lock for a fee (industry-typical 0.125% to 0.375% per extension window), re-lock at current market rate, or “worse-of” pricing (the lender applies the higher of the original lock or the current market). These are lender conventions, not federal rules. Ask your lender's expired-lock policy in advance.
Can I get a lower rate if the market drops after I lock?
Only if your lock agreement includes a float-down option. A float-down lets you re-price the locked rate lower if market rates drop by a lender-specified threshold (commonly 0.25% or more) during the lock. The option itself usually costs either an upfront fee or a slightly higher starting rate, and not every lender offers it. Ask before you lock.
Is a rate lock free?
The lock itself typically has no separate upfront charge on standard periods, but the pricing of a longer lock is higher than a shorter lock — that cost shows up as additional points or a higher rate. Extensions, float-downs, and lock-and-shop programs often have explicit fees. Everything should be disclosed on your revised Loan Estimate.
Should I lock my mortgage rate now (November 2026)?
It depends on your timeline and risk tolerance. In the current environment — rates near 7.5%, a December 9 Fed rate hike fully priced in, and 10-year Treasury yields above 5% — the balance of risk favors locking for borrowers with firm close dates in the next 30-45 days. For longer timelines or buyers not yet under contract, the calculus is more nuanced; talk to your loan officer about your specific file.
What's the difference between pre-approval and a rate lock?
Per the CFPB, a pre-approval is a conditional qualification based on your credit, income, and assets — it does not include a specific rate commitment and is not a guaranteed loan offer. A rate lock is a separate, specific price commitment for a specific loan on a specific property, typically done after you have a signed purchase contract. Our pre-approval guide walks the full ladder from pre-qualification through loan commitment.
Bottom Line
A rate lock is risk management, not prediction. In a rising or volatile market, the lock turns an uncertain future rate into a known one — and that certainty is worth something, especially on firm close dates inside the lock window. This week specifically, with rates at 7.5% and a December Fed hike widely expected, that certainty is worth more than it was a month ago.
If you're actively shopping, in escrow, or trying to decide whether to pull the trigger on a refinance, run the specific numbers on your file rather than trying to time the market. Call (877) 870-0007 or request a callback through our contact page. We will walk through the specific lock-vs-float decision on your timeline, with the actual Loan Estimate numbers and the market as it is — not as anyone wishes it were.
OnPoint Mortgage Pro is a California-licensed mortgage broker. In the mortgage industry since 2002, licensed loan officer since 2005. NMLS #888844 (Victor Santos), Company NMLS #2134550, Licensed by the Department of Financial Protection and Innovation under the California Financing Law, License #60DBO-140540. Serving California, Colorado, Florida, Idaho, Maryland, New Hampshire, South Carolina, Texas, and Virginia. Information in this article is for educational purposes only and is not legal, tax, or financial advice. Lock terms, extension fees, and float-down availability vary by lender; the figures cited here are industry-typical ranges and are not offers of specific lock terms OnPoint or any other lender can provide.
Equal Housing Opportunity.